

Your firm is not failing inspections because your team doesn't know the rules. It fails because the evidence lived in someone's WhatsApp, the acknowledgment record was never captured, and the deadline reminder pinged three people who all assumed the other one had it.
Compliance automation accounting firms in the UAE actually need is not a smarter calendar. It's a system that captures evidence when it arrives, logs decisions with timestamps, and produces an audit trail a regulator can follow without a tour guide.
Key Takeaways
- One missing document can trigger findings across three regimes — UAE accounting firms sit under FTA, PDPL, and, where applicable, DIFC or ADGM rules at once. Because the deadline logic must know which regime each client falls under, a single missing acknowledgment under PDPL can surface again when a DIFC inspector asks about it months later.
- A real audit trail needs no tour guide — It's a timestamped, access-controlled log of every document received, exception raised, and policy acknowledged, built as a by-product of the workflow rather than assembled after the fact. Human review checkpoints have to be logged too, since automation without review points fails on judgement and review without logging fails on evidence.
- Automating onboarding and exceptions cuts costs 30% to 45% — Industry analysis attributes the saving to rework hours that no longer happen and penalty exposure that no longer materializes, not to cheaper software. Firms are advised to set a matching target upfront, such as cutting evidence collection time by 30% or halving missing-documentation findings, so the first cycle has a number to report against.
Why UAE Accounting Firms Carry a Heavier Compliance Load
You are not running one compliance programme. You are running three, and they don't line up.
Federal obligations sit on every UAE accounting firm: FTA filings for VAT and corporate tax, and PDPL requirements enforced by the UAE Data Office, established under Federal Decree-Law No. 44 of 2021.
If any of your clients or your own entity sit inside DIFC or ADGM, each free zone runs its own layered regime with different inspection rights and evidence standards. A finding in one place can trigger questions in another.
Then there's the actual work: documents arriving as phone photos and scanned PDFs, mixing Arabic and English on the same page, coming through email, WhatsApp and half a dozen client portals. This is the volume at which manual review breaks.
Deadlines get missed here, not because your senior manager forgot the date, but because the evidence to close the file arrived four days late and nobody flagged it. That's the operational reality, and it sits inside the broader case for AI automation for accounting firms in the UAE shaping how modern practices scale.
Federal Decree-Law No. 45 of 2021, the PDPL, came into force on 2 January 2022. It doesn't just want a policy document on your intranet.
It wants documented handling of personal data as live evidence, produced continuously, retrievable on request.
The World Health Organization has published guidance on ethics and governance of AI for health that clinical deployments are measured against.
What Compliance Automation Actually Means in Practice
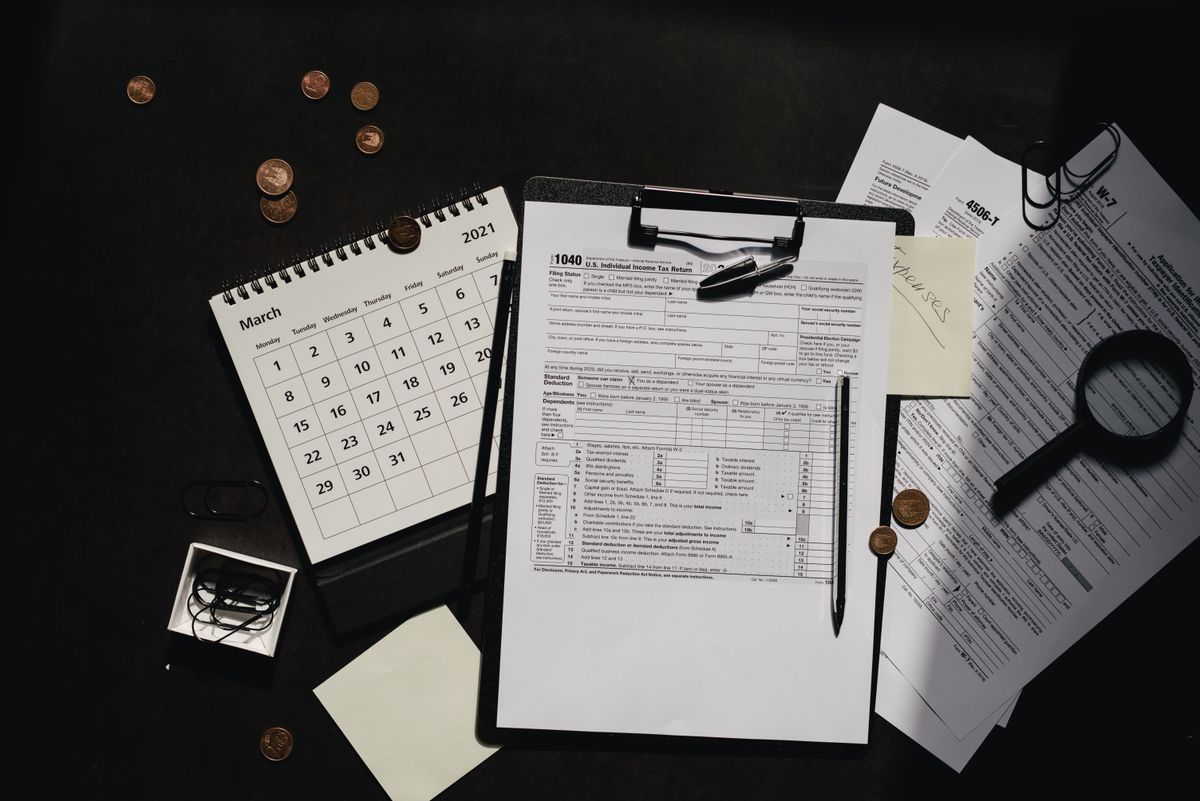
Photo: Leeloo The First on Pexels
Compliance automation has three functional layers, and most firms have only the first, done manually.
Layer one is deadline tracking. Layer two is evidence capture: pulling in the trade licence, Emirates ID, signed acknowledgment and bank statement, and attaching each to the right client file with the right timestamp. Layer three is audit trail generation: a defensible, timestamped record of every action, exception and approval a regulator can follow end to end.
Practice-management software gives you the first layer with a calendar. Compliance automation gives you all three, and it connects to what you already run.
Document portals, inboxes, CRMs and ticketing tools stay where they are. The automation layer sits across them, extracting data, standardising it, logging decisions.
If a regulator asks how you approved an exception on a client's VAT filing last March, you should not be opening a folder and narrating what you find. The log should show the request, the reviewer, the decision, the time and the evidence attached.
When a staff member needs to check status without escalating, an internal AI assistant for accounting firms can surface the same audit-ready record without pulling a partner off a client call.
The three layers build on each other, and most firms today only have the first one, running manually.
| Layer | What it does | Who delivers it today |
|---|---|---|
| Layer 1: Deadline tracking | Tracks filing and review dates on a calendar | Practice-management software |
| Layer 2: Evidence capture | Pulls trade licence, Emirates ID, acknowledgment and bank statement into the right file, timestamped | Compliance automation |
| Layer 3: Audit trail generation | Produces a timestamped record of every action, exception and approval | Compliance automation |
The UAE Regulatory Deadlines Your Automation Must Track
Deadlines don't arrive one at a time. They cluster, and the clusters overlap.
FTA VAT return windows and corporate tax obligations run on their own cycles. Neither is negotiable, and a miss creates a documented gap that survives into every subsequent inspection.
PDPL data review cycles and staff acknowledgment records are also time-bound, not one-time setup tasks. If your firm sits inside DIFC or ADGM, add layered obligations on top of the federal load.
One automation stack has to handle every regime the firm is subject to, which means the deadline logic must know which client sits in which regulatory zone. A single missing acknowledgment can create a finding under PDPL that a DIFC inspector then asks about six months later.
The critical design point: deadline automation triggers evidence requests before the deadline, not on the day. Missing evidence, not missed dates, is what shows up most often in UAE inspection findings.
If you ask the client for their updated Emirates ID on filing day, you have already lost. The workflow should chase evidence on a schedule, log every request and response, and escalate before the day arrives.
Building an Audit Trail That Survives Scrutiny
An audit trail is a timestamped, access-controlled log that regulators can follow without asking you to explain it. That's the whole definition.
When a document is received, the system logs when, from whom, into which client file, and who reviewed it. When an exception is raised, the system logs the reviewer, the decision, the time and the attached evidence. When a policy is distributed, staff acknowledgments are captured with a timestamp against each employee record.
Access reviews, policy distribution records and staff acknowledgments are the evidence types most commonly missing in UAE inspections. They aren't glamorous, but they are what a regulator looks for first, and they are the easiest wins for automation.
Human-in-the-loop checkpoints have to be logged too. Automation without human review points fails on judgement calls; human review without logging fails on evidence.
You need both, visible in the same trail. The same principle applies to routing decisions on inbound client mail: when automated email triage for accounting firms sends a query to the right partner, that routing decision is a timestamped record too.
Clinics licensed in Dubai answer to the Dubai Health Authority for how patient information is collected, stored and communicated.
Evidence Collection: From Manual Chase to Automated Capture
Photo: cottonbro studio on Pexels
The typical evidence bundle is trade licences, Emirates IDs, VAT invoices and bank statements, arriving as photos and PDFs through email, WhatsApp and client portals, often with Arabic and English on the same page. The volume is the problem, and the format is the second problem.
Set a measurable target before implementing anything: reducing evidence collection time by 30% or cutting missing-documentation findings by half. That target becomes both the acceptance test for the build and the number you report to leadership when the first cycle closes.
Industry analysis reports that firms streamlining onboarding and exception management have seen cost reductions of 30% to 45%. That saving isn't from cheaper software; it's from rework hours that no longer happen and penalty exposure that no longer materialises.
Evidence automation starts earlier than most firms think. The same trade licence and beneficial-owner data you need for onboarding should already be captured during qualification. Firms handling that through AI lead qualification for accounting firms inherit a partial evidence file the moment the engagement letter is signed.
How to Implement Without Replacing Your Systems
You don't need a new system of record. You need a governed layer on top of the ones you have.
Start with baseline metrics. Before touching any workflow, set the target: what does success look like at day 90?
If the goal was to cut missing-documentation findings by half and after one full cycle they haven't moved, the build has a problem you need to diagnose, not paper over.
Days 31 to 60 are for build, test and document. Workflows connect to real firm data and get tested against actual compliance events, not synthetic ones. No workflow goes live until its own audit trail has been verified end to end.
Multilingual handling is not optional. Documents that mix Arabic and English on the same page need extraction logic that works across both scripts. A system built for English-only documents will miss evidence, and missed evidence is a finding.
Train the team alongside the build. Compliance discipline breaks the moment staff route around an automated checkpoint because they don't understand what it's flagging.
If you want an outside view on which of your workflows are ready to automate first, book a free 30-minute consultation.
Measuring Whether It Is Actually Working
Three numbers tell you whether it's working.
End-to-end time savings per compliance cycle. Reports show time savings in the compliance space can reach up to 75% with the right tooling. Track this per cycle against the baseline you set on day zero.
Cost per cycle, measured as rework hours and penalty exposure avoided. Licence cost alone is the wrong denominator. If you've cut two days of partner rework a month and avoided one PDPL finding, the maths is settled.
Missing-documentation findings per audit period. If this number is not falling after your first full cycle post-implementation, the evidence capture step is broken and needs diagnosis before the next filing window closes.
One more thing regulators will look at: the audit trail of the automation itself. A compliance automation system that cannot show its own log is the first thing an inspector will question.
Related reading
FAQ
Does the UAE require digital audit trails?
Yes. PDPL requires documented data-handling as live, retrievable evidence, and FTA obligations expect records produced quickly on request. Paper cannot replace a timestamped log a regulator can follow end to end.
Which UAE bodies inspect an accounting firm's compliance records?
The FTA covers tax obligations; the UAE Data Office covers PDPL. DIFC and ADGM each run their own regimes with distinct inspection rights. A firm across zones needs one system that satisfies all.
How does automation handle Arabic and English documents?
Extraction logic must work across both scripts on the same document. A system built for English-only extraction will miss half the data on a bilingual trade licence.
What separates a deadline reminder from compliance automation?
A reminder tells you a deadline is coming. Compliance automation tracks the deadline, triggers evidence collection before it, captures the evidence when it arrives, logs every review and exception, and produces the audit trail as output.
Can one system cover FTA, PDPL, DIFC and ADGM?
Yes. A fragmented stack with separate tools per regime creates gaps at the joins, which is where inspection findings live. One governed layer aware of which regime each client sits under is the model to build toward.


